The goal planner asks for a target in rupees. Humans type the number from a listing site or a wedding WhatsApp quote a today number then are shocked when someone tells them to inflate it. The page itself will not. It treats Goal Amount as the corpus you need on the end date. This note is the fork: today’s rupees versus future rupees, because I keep seeing people skip inflation and call themselves conservative.

The planner does not inflate. You do.
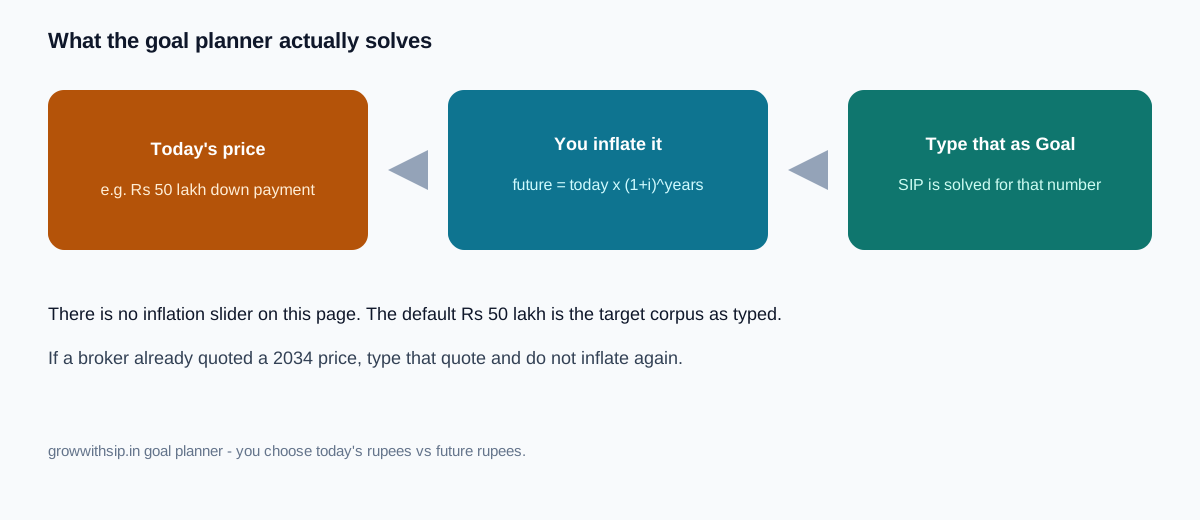
Required SIP = Goal × r / [((1 + r)n − 1) × (1 + r)], with r as monthly assumed return and n as months. Required lumpsum today is Goal / (1 + annual return)years. There is no CPI series and no inflation slider. The child-education preset fills ₹50 lakh and 15 years. That ₹50 lakh is the target as typed.

Two valid methods, not both
Method A: Goal is in today’s rupees. Multiply by (1 + i)years, type the result as Goal Amount, then solve SIP at your assumed return. That is the honest “₹50 lakh of today’s purchasing power for a down payment.”
Method B: You already estimated the future sticker (broker said ₹80 lakh in 2032). Type ₹80 lakh. Do not inflate again, or you plan for a palace. Method B is fine if the future price is researched. It is not fine if the ₹80 lakh was a vibe.
Worked: ₹50 lakh of today’s goods in 15 years
Leave assumed return at the page default of 12% an illustration, not a forecast. Same engine as the live planner:
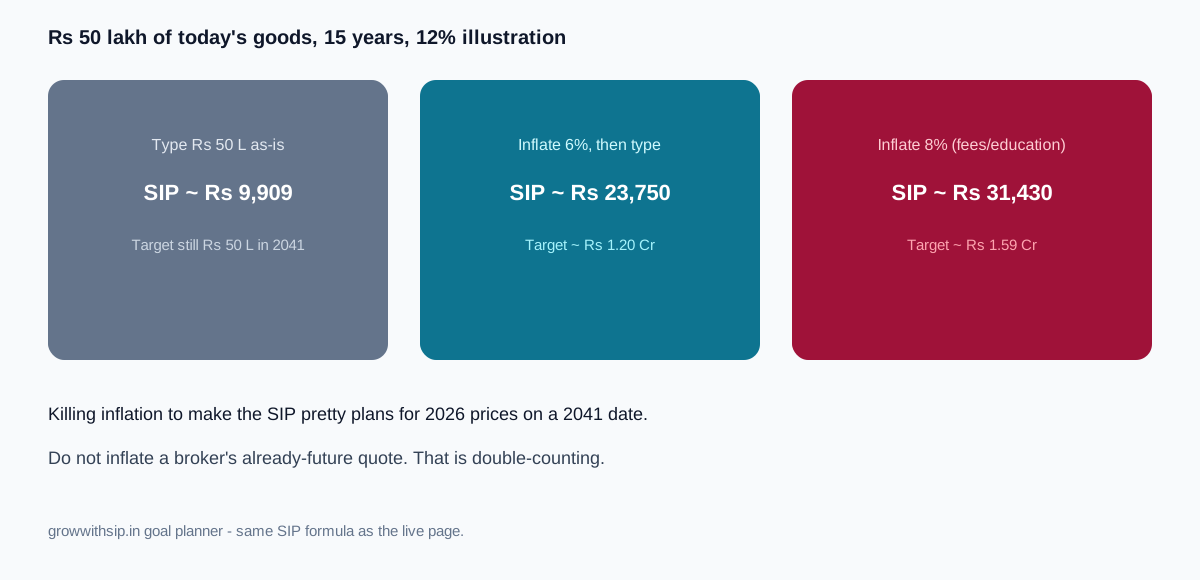
| What you type as Goal | Required SIP at 12% |
|---|---|
| ₹50 lakh as-is (2041 still ₹50 lakh) | about ₹9,909 a month |
| Inflate 6% → about ₹1.20 crore | about ₹23,750 a month |
| Inflate 8% → about ₹1.59 crore | about ₹31,430 a month |
A house down payment of ₹50 lakh in eight years at 6% is about ₹79.7 lakh. Typing ₹50 lakh needs about ₹31,000 a month at 12%. Typing the inflated ₹79.7 lakh needs about ₹49,300. That gap is the whole point of this page.

Education and healthcare inflate faster
Headline 6% is a CPI stub. A foreign-education goal may need 8–10% even if MOSPI prints 4%. Type a hotter rate and look at whether the SIP still fits salary. If it does not, the answer is a smaller goal, a later year, a step-up SIP, or a lumpsum from a bonus - SIP vs lumpsum not a higher assumed return.
Retirement is the same class of problem with a lifestyle in today’s rupees. Use the retirement calculator for “₹X a month today, growing with inflation after you quit.” That tool does inflate expenses. Do not mix its corpus with a goal-planner SIP that assumed a different inflation and a different end date, then add them like grocery items.
Presets are not research
Child education / wedding / house presets fill round numbers so you can see the machine move. Replace them with your quote. A preset ₹25 lakh wedding is not your family. The halfway-year marker is when this constant-return path crosses 50% of the goal you typed.
Read inflation on growwithsip if you want the deflator used on SIP and retirement. This page is only: do not double-count, and do not skip inflation to make the SIP pretty.