What step-up adds and what it does not
Each year the monthly debit rises by the step-up percent you type, then the same SIP loop runs. Two illustrations are stacked: a return slider and a contribution hike. A 10% step-up plus 12% return is not a promise of ₹2 crore.
If the stepped debit already breaks next year's budget, the 12% screenshot was comfort. Inflation still deflates the final pile. Treat both sliders as illustrations.

The debit grows even if markets do nothing
Motion is the same maths as the worksheet. Reduced-motion browsers skip the grow.
Calculator education
When to use this calculator
Use this page when you expect the monthly debit to rise with salary, and you want to see how that hike plus a constant return illustration interact.
How to read your result
Invested amount is the sum of all stepped monthly contributions. Total value compounds those contributions monthly at the return you typed. Estimated returns are the difference.
A 10% step-up stacked on a 12% return is two illustrations, not a ₹2 crore promise. Check year-five debit against take-home.
Key assumptions and limitations
- The step-up happens once a year; the SIP never misses a month.
- Return and inflation (if used) are constant rates you type.
- The engine does not know whether next year’s hike will actually clear the bank.
Common mistakes
- Raising the return slider when the stepped EMI already breaks the budget.
- Ignoring inflation on a larger headline corpus.
- Assuming every platform will auto-hike the mandate the way this worksheet does.
Related guides
Related calculators
Step-up plus assumed return is two planning knobs. Neither is a forecast of salary or markets. Full disclaimer.
Author / methodology
What I check on a step-up
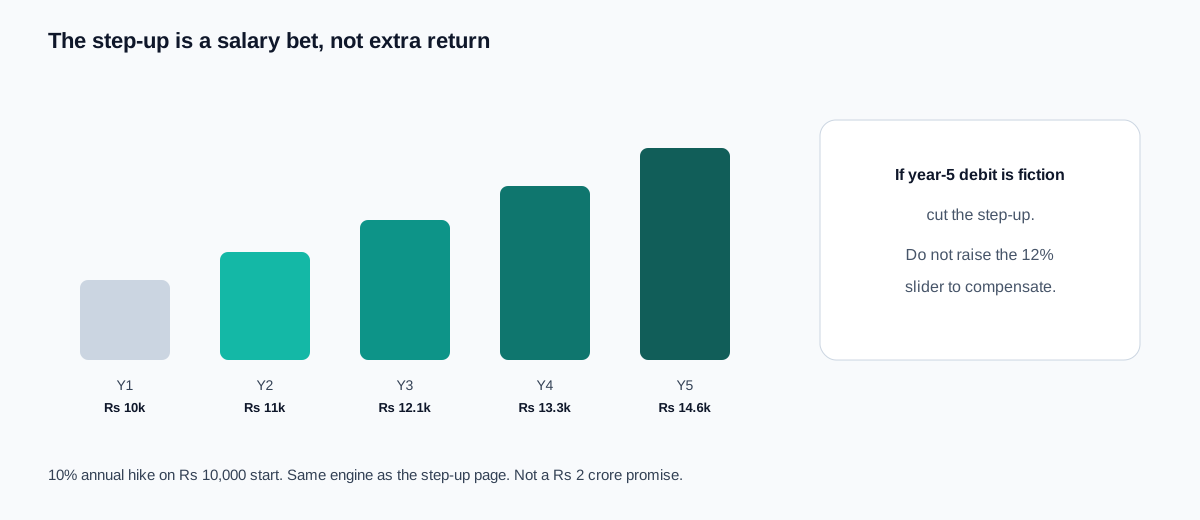
- Year-5 debit versus take-home. If that number is fiction, I cut the step, not raise the return.
- A 10% step plus 12% is two illustrations stacked. It is not a ₹2 crore promise.
- If the hike already bounced last year, I model missed months on the SIP page instead.
The stepped debit is a contract with your future salary
Fund houses will happily raise the mandate. Your emoluments might not. The 12% slider does not know that.
| Year of the SIP | What usually breaks first | What this page still assumes |
|---|---|---|
| Year 2–3 | You forget the mandate grew and the bank bounces | Every hike posts on time at the typed percent |
| Year 5+ | Rent, EMI, or a child costs more than the step-up | The same return every month, no pause |
| The AMC | Can reject a mandate change; cannot raise your CTC | Not modelled |
If year-5 debit already looks fictional, cut the step-up. Do not raise the return slider to compensate.
Flat SIP vs 10% annual step-up. Same engine as this page.