Lifestyle in today's rupees, corpus in future rupees
You describe monthly expenses as they feel today. The engine inflates them to retirement age, sizes a corpus for the years after that, then solves a SIP to that corpus. That is the opposite of typing a round crore because it looks nice.
Post-retirement return and life expectancy are yours to stress. Do not add this corpus to a goal-planner SIP that used different inflation and a different end date. Inflation on this site.
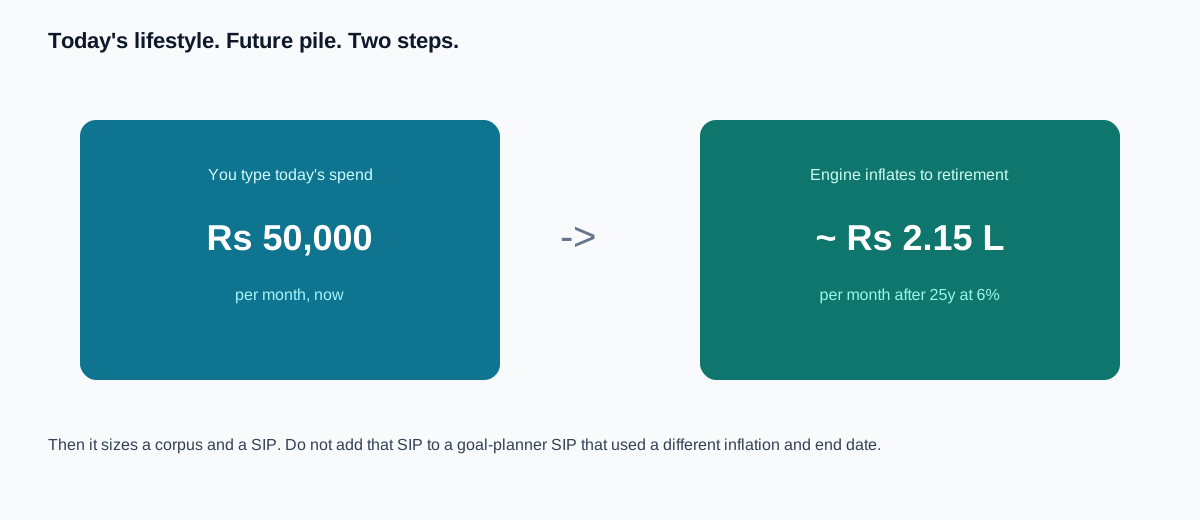

Today's spend, inflated
Motion is the same maths as the worksheet. Reduced-motion browsers skip the grow.
Calculator education
When to use this calculator
Use this page to turn today’s monthly expenses into an inflated cost at retirement, a corpus that could support those years, and a monthly SIP that might reach that corpus under assumed returns.
How to read your result
Required corpus is a planning pile in future rupees, using post-retirement return and life expectancy in the code. Required monthly SIP is the contribution that hits that pile at the pre-retirement return you typed.
Do not add this SIP to a goal-planner SIP that used a different inflation and end date. This page sizes a pile; it does not spend it (that is SWP).
Key assumptions and limitations
- Today’s expenses inflate to retirement at the inflation rate you type.
- Post-retirement return and life expectancy are planning guesses in the engine.
- Pre-retirement SIP return is a constant you type — not a forecast.
Common mistakes
- Typing a round crore because it looks nice, instead of inflating lifestyle.
- Using last year’s best market year as the accumulation return.
- Treating the corpus as spendable cash without an SWP or deposit plan.
Related guides
Related calculators
Retirement numbers here are chained assumptions: inflation, returns, and lifespan. None of them is a prediction. Full disclaimer.
Author / methodology
What I check on a retirement pile
- The lifestyle is today’s rupees, inflated to the retirement year. A round crore is not that job.
- I do not add this SIP to a goal-planner SIP that used a different inflation and end date.
- Drawdown is a separate SWP problem. This page sizes a pile; it does not spend it.
No company sells you this corpus you assemble it
EPF, NPS, PPF, and market SIPs are different counterparties. This page sizes one pile, then a SIP to that pile.
| Sleeve | Typical counterparty | What breaks the size |
|---|---|---|
| Salary EPF / EPS | EPFO + employer | Job changes, unemployment, and the 8.25%-class rate is not this SIP slider |
| NPS / annuity | PFRDA + insurer at exit | The 40% annuity haircut this retirement page does not apply |
| Taxable equity / debt SIP | AMCs | Sequence risk in the drawdown decade use the SWP page separately |
Do not add this required SIP to a goal-planner SIP that used a different inflation and a different end date.
This page grows today’s lifestyle to the retirement year, then sizes a corpus. A round crore is not that job.